Why are so many jewellery retailers in India struggling with corporate profitability?
It’s a question that comes up often. And the answer reveals something deeper about how the Indian jewellery market operates.
Most retailers assume the challenge lies in competition or rising marketing spend. But the real constraint is far more structural.
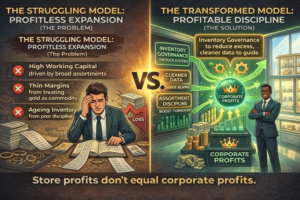
Indian jewellery retail operates under three realities:
1. Extremely high working capital requirements driven by broad assortments and region-specific demand patterns.
2. Thin gross margins because gold is treated largely as a commodity rather than a branded product.
3. Ageing inventory caused by subjective buying decisions and weak assortment discipline.
This creates an interesting contradiction.
Individual stores may appear profitable at the EBITDA level, yet the corporate P&L struggles under the weight of financing costs, ageing inventory, and operational overheads.
The store performs.
The company doesn’t.
Now compare this with markets like China, the UK, or the US—where stronger brand premiums, standardized assortments, and higher diamond penetration create healthier margin structures and better inventory productivity.
The implication is clear:
In India, profitability will not come from simply opening more stores.
It will come from tighter inventory governance, cleaner data, sharper assortment planning, and faster inventory velocity.
That is where the real transformation in jewellery retail begins.